Why a profitable company can still run out of cash
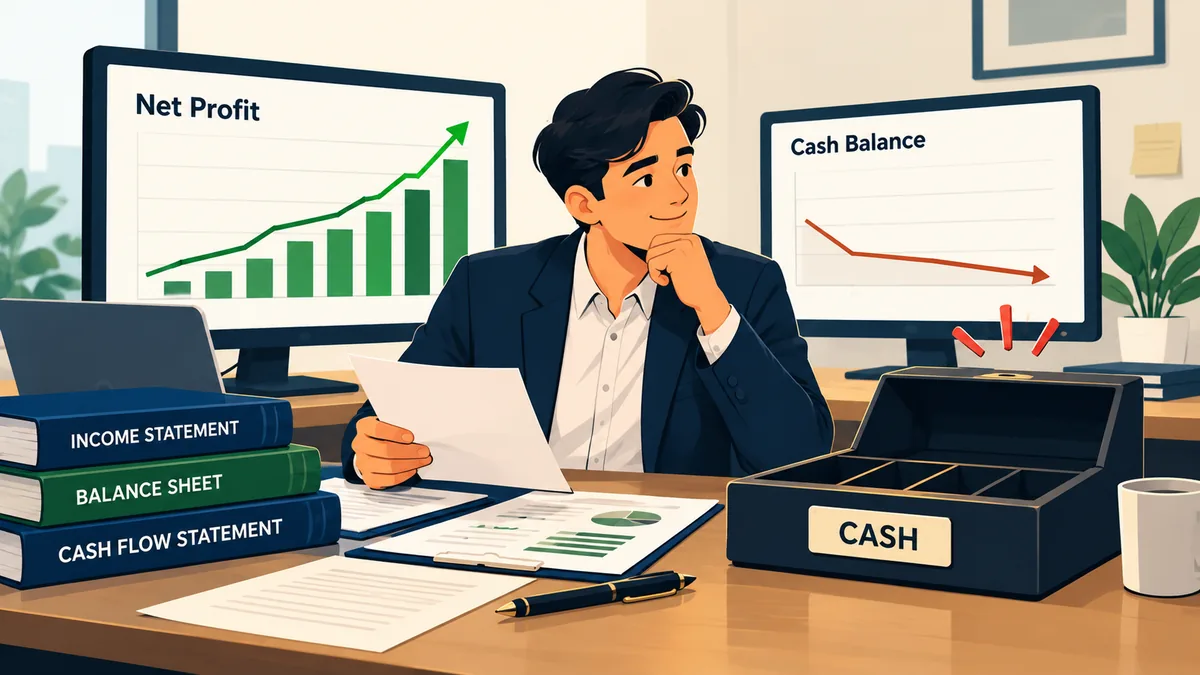
Profit is an accounting opinion; cash is a fact. This is how a company can be profitable on paper and still unable to pay its bills.
Gajji Srinath, Founder, The Valuation Node
Key takeaways
- Profit and cash diverge through working capital, capex, and financing.
- A fast-growing firm can consume cash faster than it earns it.
- Short-term funding for long-term assets can break a profitable company.
- Always read the cash flow statement alongside the P&L.
Profit is an opinion, cash is a fact
A common belief: if a company is profitable, it has money. If profits are growing, it must be getting richer. Most of the time that is roughly true. When it is not, the gap can sink a company.
Profit is calculated using accrual accounting. Revenue is recorded when a sale happens, not when the customer pays. Expenses are matched to the period they relate to, not to when the bill is settled. A machine bought for ₹50 crore is spread over its useful life as depreciation. These rules make profit a better measure of how a business performs. They also mean profit rests on judgment.
Cash is simpler. It is the money that actually moved in and out of the bank. A company pays salaries, suppliers, lenders and taxes in cash, not in profit. That is why a company can report rising profits and still fail to pay its bills.
Three places cash goes missing
1. Working capital. Before a company collects cash from a sale, it usually has to buy materials, hold stock and wait for customers to pay. That money is tied up in inventory and receivables, minus what the company itself owes suppliers. This is net working capital. When sales grow, it grows with them.
2. Capital expenditure. Factories, machines and stores are paid for upfront. Profit feels the cost slowly, through depreciation. Cash feels it at once.
3. Debt repayment. Interest passes through the profit and loss statement. Repaying the loan itself does not. A company can show healthy profit after interest and still face a principal repayment it cannot fund.
A worked example: growing into a cash crunch
Illustrative numbers, rounded. Take a company with these features:
- Net profit margin of 10%. To keep it simple, we treat profit as cash profit before working capital, and ignore depreciation and tax timing.
- Customers pay in 90 days, inventory sits for 60 days, and suppliers are paid in 30 days. That leaves about 120 days of sales tied up, roughly a third of annual revenue. We use 33% to keep the arithmetic clean.
- Sales grow 40% a year.
| Year 1 | Year 2 | Year 3 | |
|---|---|---|---|
| Revenue (₹ cr) | 100.0 | 140.0 | 196.0 |
| Net profit (₹ cr) | 10.0 | 14.0 | 19.6 |
| Net working capital (₹ cr) | 33.0 | 46.2 | 64.7 |
| Increase in working capital (₹ cr) | 13.2 | 18.5 | |
| Capex (₹ cr) | 6.0 | 8.0 | |
| Cash left after both (₹ cr) | -5.2 | -6.9 |
Over years two and three, the company reports ₹33.6 crore of profit. Its cash falls by ₹12.1 crore.
Nothing is wrong with the business model. The margin is fine and the customers are real. The company is simply growing faster than its profits can fund. In this example, even with no capex at all, growth above about 43% a year would absorb every rupee of profit.
Compare the same company growing at 10% a year. Year-two profit is ₹11 crore, the working capital increase is only ₹3.3 crore, and even after the same ₹6 crore of capex, it generates ₹1.7 crore of cash. Slower growth, more cash.
The fast-growing version must borrow or raise equity to keep going. If lenders turn nervous at the wrong moment, a profitable company can fail.
The second squeeze: debt that comes due
Growth is one route to a cash crunch. Debt structure is another.
Suppose a company funds long-term assets, such as a plant or a book of five-year loans, with short-term borrowing that must be rolled over every few months. As long as lenders keep rolling it over, nothing shows up in the profit and loss statement. The day they stop, the company needs cash it does not have.
Indian markets saw this in 2018. After IL&FS defaulted, short-term funding dried up, and several non-banking finance companies that were profitable on paper came under severe stress. Their main problem was not that their loans were losing money. It was that their liabilities came due before their assets turned into cash.
The notes to the accounts include a maturity analysis of financial liabilities, required under Ind AS 107. It shows how much debt falls due within one year, in one to five years, and beyond. Compare the near-term amount with cash, liquid investments and expected operating cash flow.
Cases that break the simple story
A gap between profit and cash is not always a warning.
Some businesses run on negative working capital. Many retailers, consumer brands with strong distributor terms, and subscription businesses collect cash from customers before they pay suppliers. For them, growth releases cash instead of consuming it.
Some cash burn is a deliberate choice. A company building capacity ahead of demand will show weak free cash flow for a few years. The real question is whether that investment earns more than its cost of capital, not whether today's cash flow is negative.
And one weak year proves little. The timing of large orders, a delayed government payment or a year-end inventory build can all distort a single period.
Reading for cash, not just profit
- Put CFO next to net profit for five years. Persistent gaps need an explanation.
- Track the cash conversion cycle. Receivable days plus inventory days minus payable days. A steady rise means more cash is tied up per rupee of sales.
- Calculate free cash flow. CFO minus capex. This is what is left to repay debt, pay dividends or fund growth.
- Compare growth with self-funding capacity. If sales grow much faster than profit can fund, find out where the rest of the money is coming from.
- Read the debt maturity table. Match near-term repayments against liquid resources.
The reframe
Profit tells you whether the business model works. Cash tells you whether the company will survive long enough to prove it. Read both, and pay closest attention when they disagree.
Sources
Figures and claims come from the sources named in the text and in the methodology note above: company filings, exchange disclosures, and rating agency reports, as cited. See the editorial philosophy for how sources are chosen.
Cite this article
Gajji, S. (2026). "Why a profitable company can still run out of cash." The Valuation Node. https://valuationnode.com/analysis/financial-analysis/profitable-but-out-of-cash
Related
Working Capital Trends in Indian Manufacturing Companies
Ten years of working capital data for five large manufacturers. Three run on suppliers' money; two now tie up much more cash than they did in FY17.
MethodologyHow to Read a Company Before Investing: A Financial-Statement Framework
A seven-layer framework for reading an Indian company's annual report, starting with the business and ending, not starting, with the share price.
MethodologyFive red flags in financial statements
Five warning signs in an annual report, how to check each in minutes, and why a red flag is a question to answer, not a verdict.
Discussion
Commenting as a guest. Add a name if you like, or leave it blank to post as Anonymous. Log in to comment as yourself.
Educational analysis, not investment advice. The author may hold positions in securities discussed; where relevant, this is stated above. See the disclaimer.
Stay in the loop
Roughly one email per month. No spam, no upsells.