Industry analysis
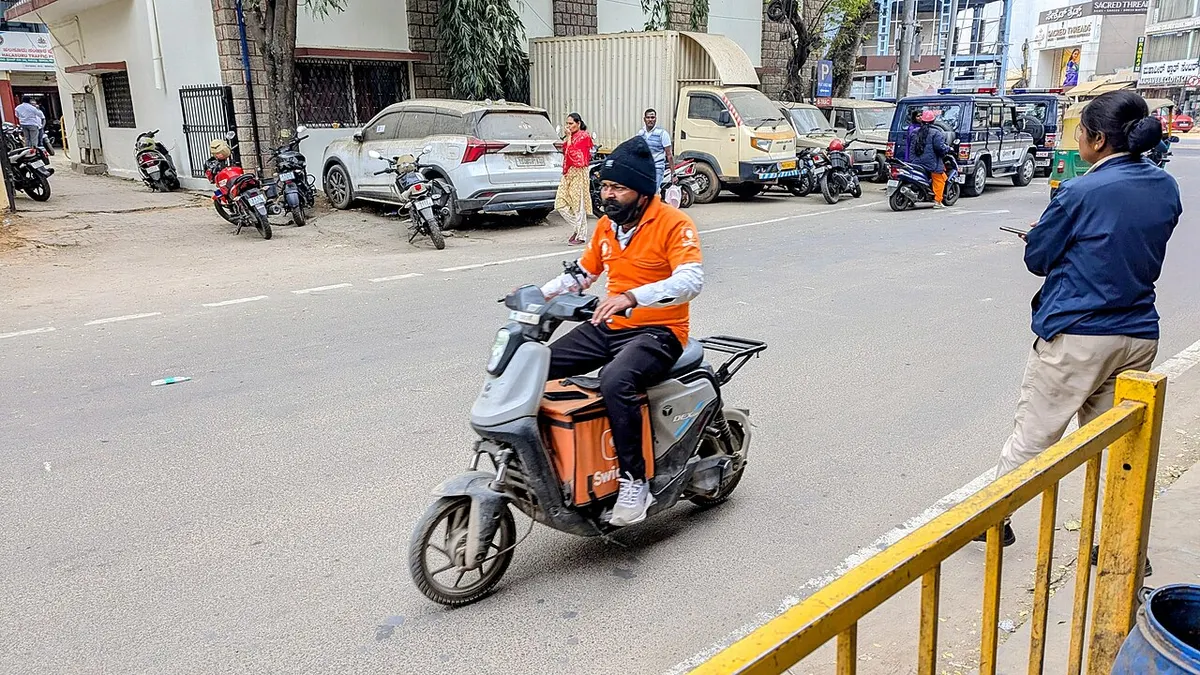
Quick Commerce Unit Economics: Orders, Margins and Delivery Costs
Ten-minute delivery is impressive. Whether it is profitable depends on a few numbers per order and per store. Here is how to read them.
5 min readRead more
14 pages carry this tag.
Ten-minute delivery is impressive. Whether it is profitable depends on a few numbers per order and per store. Here is how to read them.
Most people start with the share price and the P/E. A better order starts with the business, works through the statements, and looks at the price last.
Revenue growth is the number that makes headlines. Free cash flow is the number that pays investors. The link between them is the return a company earns on what it reinvests.
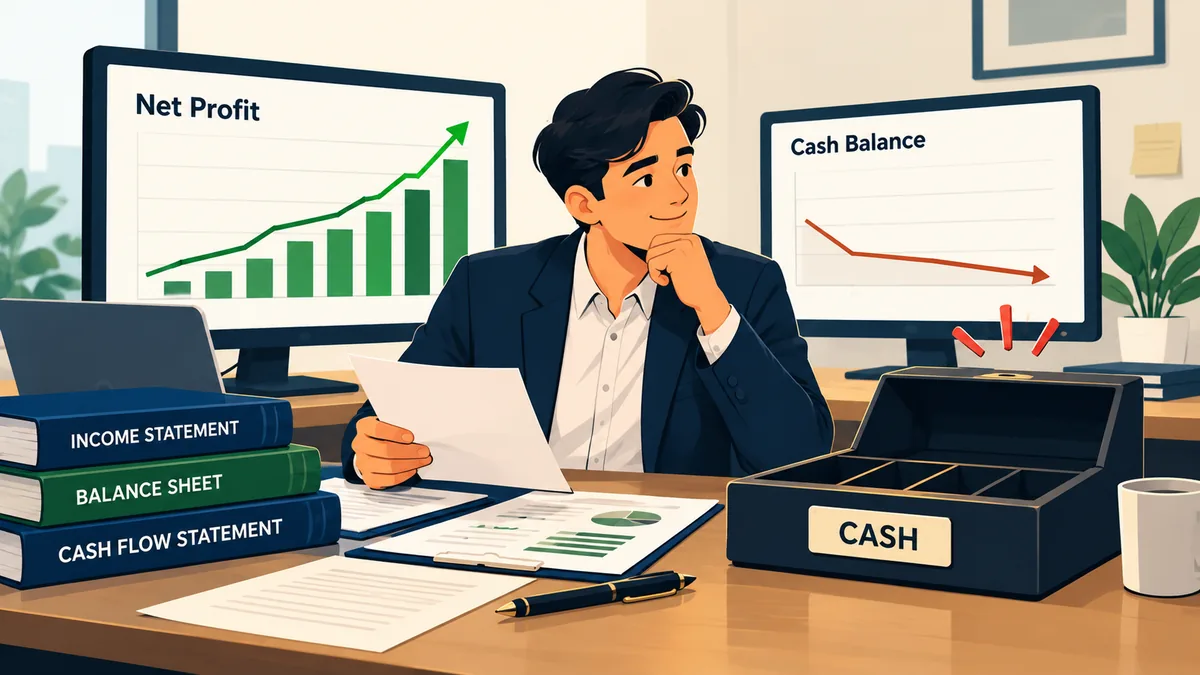
Profit is an accounting opinion; cash is a fact. This is how a company can be profitable on paper and still unable to pay its bills.
Accounting problems rarely show up as one dramatic number. They show up as small places where the statements stop agreeing with each other. Here are five to check first.
Working capital decides how much cash a company must tie up to grow. Ten years of data for five large Indian manufacturers show very different models, and some quiet shifts worth noticing.
"Debt-free" is one of the most reassuring phrases in an investor presentation. Sometimes it signals strength. Sometimes it hides idle cash, disguised borrowing, or a business no lender will touch.
Profit is an opinion, cash is a fact, and one year of cash flow is a snapshot. It takes three years for the snapshot to become a story.
Why cash is harder to fake than profit: the three sections of the cash flow statement, free cash flow, and checks on operating cash quality.
How the P&L, balance sheet and cash flow statement feed into each other, and how to build a three-statement model that balances.
Operating working capital and the cash conversion cycle: how to work out DIO, DSO and DPO, sector benchmarks, negative working capital and manipulation.
The CFO to PAT ratio compares five years of cash flow from operations with five years of reported net profit. It is the simplest anti-fraud check in fundamental analysis.
Free cash flow is operating cash flow minus the cash the business is forced to reinvest to keep running and growing. It is the money that is genuinely surplus.
Cash flow per share is operating cash flow divided by the number of shares. Set next to EPS, it shows how much of each share's reported profit actually arrived as cash.
Related topics: Valuation, DCF, Relative valuation, Cost of capital, Financial statements, Earnings quality, Red flags, Ratios